This site uses cookies to store information on your computer. Some are essential to make our site work properly; others help us improve the user experience. We value your privacy and encourage you to read Kapitus’s Privacy Policy to learn more about how we use cookies and how we may collect and use visitor data. By continuing to use this site, you consent to the placement of these cookies. If you wish to limit this tracking, please select your preferences below or broadcast a Global Privacy Control (GPC) signal.


  • Link to LinkedIn
  • Link to X
  • Link to Youtube
  • Link to Instagram
  • Link to Facebook
Call now: (800) 780-7133Login
Kapitus
  • Solutions
  • Products
    • Business Loans
    • Line of Credit
    • Revenue Based Financing
    • Equipment Financing
    • Purchase Order Financing
    • SBA Loans
    • Invoice Factoring
  • Partnerships
  • Resource Center
  • About
  • Contact
  • Login
  • APPLY NOW
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Tag Archive for: small business loans

How to Prepare for a Business Loan: What Lenders Look For

Fast Business Loans
by Kapitus7 minutes / October 16, 2026
  • Share on Facebook
  • Share on X
  • Share on LinkedIn
  • Share on Tumblr
  • Share on Vk
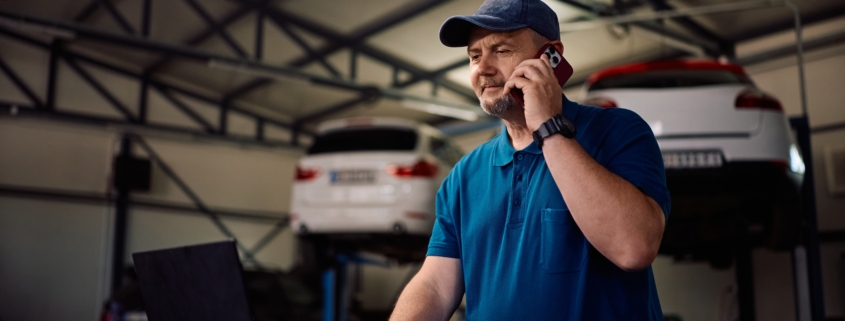
Auto mechanic talking on the phone in his repair garage while researching how to prepare for a business loan for his small business.

Getting your first business loan is an exciting milestone for small business owners. It can provide the capital you need to grow your business and improve your cash flow. However, before you apply, it’s important to understand what to expect so an offer doesn’t catch you off guard.

Assessing your business before you apply, especially by reviewing your cash flow history, can help you avoid surprises when it comes to loan amount, interest rate and the overall cost of financing.

It’s worth noting that when lenders advertise rates by stating that “you could get a loan with as little as X% interest,” it doesn’t mean that everyone qualifies for those terms. Your actual rate will depend on how risky the lender considers your business, particularly your ability to pay back the loan. If you are considering applying for a loan, you should be ready to address the factors lenders use to assess that risk.

Key Takeaways

  • Strengthen cash flow before applying: Lenders evaluate at least six months of bank statements to gauge risk, meaning that waiting for temporary negative cash flow to rebound can secure lower interest rates and better terms.
  • Organize essential financial paperwork early: Gathering tax returns, bank statements, credit reports and a clear usage plan accelerates underwriting while maximizing your approval odds.
  • Balance funding speed against borrowing costs: Comparing traditional banks and alternative lenders allows you to weigh rapid turnaround times against higher interest rates, additional fees and stricter risk requirements.

Review Your Cash Flow Before Applying for a Business Loan

Whether you are applying for a loan with a traditional bank or alternative lender, the lending agent will want to see at least six months of your business’ bank statements. These statements help the lender evaluate your cash flow, which is the amount of money that is flowing in and out of your business on a regular basis.

It’s important to know that if you’ve had recent months of negative cash flow, it can strongly impact the interest rate on your loan if a lender approves your application. In this case, the lender may offer you a higher interest rate than you initially expected.

If those negative months were temporary hiccups, consider waiting a few months before applying for business financing. A stronger cash flow history can improve your chances of securing better terms.

How Does Time in Business Affect Business Loan Eligibility and Terms?

Alternative lenders often require a minimum of two years in business for most of their financing products, while some traditional banks require at least three years. Many small business owners look to secure financing as soon as their businesses reach those thresholds. However, the age of your business will affect your cost of capital, no matter the type of financing product you are seeking, be it a term loan, business line of credit, revenue-based financing or equipment financing.

Generally, the younger your business, the higher the risk your potential lender will view you as. So, if you’ve only been in business for two years, don’t be surprised if you don’t get the interest rate or loan amount that you were expecting.

What Documents Do You Need to Apply for a Business Loan?

One of the biggest impediments small business owners face when seeking financing is not having the proper paperwork. While alternative lenders often require less paperwork than traditional banks, it’s still important to have the proper documentation ready for both. Lenders commonly require the following documents:

  • Tax returns: Past tax returns will show your potential lender your business’ annual taxable revenue for the past few years, which is often crucial in determining the terms of your financing.
  • At least 6 months of bank statements: Your business’ cash flow history will have a direct impact on the terms of your financing. This is especially important for products like revenue-based financing, which takes a percentage of your future sales in exchange for a lump sum of cash up front.
  • A plan for how you’ll use the financing: For products such as term loans or equipment financing, you should provide a clear plan for how the funds will support business growth and increase revenue. This will help the lender assess the risk of lending your business money and will have a strong impact on not only your chances of approval, but also the interest rate and fees the lender offers you.
  • A detailed credit report: If you get approved for a loan, the cost of capital will depend heavily upon your credit scores. It’s important to contact one of the three main credit bureaus — Equifax, Experian and Transunion — to obtain your credit report to ensure there are no mistakes bringing your score down. Both your FICO and business credit scores will help determine the cost of the capital you are offered on your loan. If you have poor credit, you may want to take steps to improve it before you apply for a loan.

Compare Small Business Lenders, Interest Rates and Fees

Before choosing a financing option, take the time to shop around. For a quick turnaround, an alternative lender may be the best bet. These lenders typically require less paperwork, slightly lower credit scores and offer faster funding times than traditional banks — but generally charge higher interest rates and fees.

Shopping for a lender should be no different than shopping around for any other product. Whether you choose an alternative lender or a traditional bank, make sure you shop around for the best rates, fees and loan amounts.

If you do choose an alternative lender, be sure to read reviews and check their standing with the Better Business Bureau to ensure you are not dealing with a bad actor.

Set Realistic Expectations for Your Business Loan Offer

Before you apply for financing, set realistic expectations by considering the key factors that lenders evaluate before offering you a loan: time in business, cash flow history and proper documentation. These elements play a major role in determining whether you are approved for a loan and the interest rates and fees you’ll be offered. If your business is lacking in any of these areas, consider delaying your application for a few months or be prepared for higher rates and fees than you had initially anticipated.

FAQs

How does cash flow affect business loan approval?

Lenders review at least six months of bank statements to gauge repayment capability. Recent months of negative cash flow signal elevated risk, resulting in higher interest rates or smaller offers. Waiting for temporary dips to rebound can help you secure more favorable borrowing terms.

What documents do you need to apply for a business loan?

Lenders typically require recent tax returns, six months of bank statements, credit reports and a loan usage plan. These records verify revenue stability, cash flow and repayment ability. Clean financial documentation and solid credit scores ensure faster approvals and lower borrowing rates.

What factors determine business loan interest rates?

Lenders set interest rates based on cash flow history, time in business, credit scores and financial paperwork. Advertised rates represent best-case scenarios rather than guarantees. Proving strong revenue and reliable repayment capacity helps you qualify for the most competitive financing terms.
Kapitus

Kapitus

  • Twitter
  • LinkedIn
  • Facebook
  • Youtube
  • Instagram

Read More Articles >>

Related Posts

Our trending spaces

October 19, 2026 Fast Business Loans

How Much Working Capital Does Your Small Business Need?

October 19, 2026/by Kapitus
October 16, 2026 Fast Business Loans

How to Prepare for a Business Loan: What Lenders Look For

October 16, 2026/by Kapitus
October 14, 2026 Fast Business Loans

How Cash Flow Impacts Business Loan Approval: What Lenders Look For

October 14, 2026/by Brandon Wyson
Load more
https://kapitus.com/wp-content/uploads/2026/10/shutterstock_2827037357-scaled.jpg 1707 2560 Kapitus https://kapitus.com/wp-content/uploads/2024/01/Kapitus_Logo_white-220.webp Kapitus2026-10-16 11:00:262026-10-13 12:01:03How to Prepare for a Business Loan: What Lenders Look For

How Cash Flow Impacts Business Loan Approval: What Lenders Look For

Fast Business Loans
by Brandon Wyson7 minutes / October 14, 2026
  • Share on Facebook
  • Share on X
  • Share on LinkedIn
  • Share on Tumblr
  • Share on Vk
Image of a small business loan application to demonstrate How Cash Flow Impacts Business Loan Approval.

Business owners seeking financing often focus on credit scores, collateral or pitch decks, but lenders prioritize one make-or-break factor above all: cash flow. At its core, cash flow answers an underwriter’s most critical question: Can your business comfortably repay what it borrows?

Here is a closer look at why cash flow drives loan approvals, how lenders measure it and practical steps you can take to strengthen your numbers before applying.

Key Takeaways

  • Prioritize consistent cash flow: Lenders look for stable cash inflows and manageable expenses that demonstrate your ability to repay financing, even during slower periods.
  • Give lenders a clear financial picture: Prepare accurate cash flow statements and bank records, explain seasonal fluctuations and avoid inflated add-backs that could undermine your credibility.
  • Strengthen cash flow before applying: Speed up customer payments, negotiate vendor payment schedules and reduce non-essential spending to improve cash stability and support your financing application.

Why Is Cash Flow Important for Business Loan Approval?

Business financing and cash flow are tightly linked, which is why cash flow sits at the center of nearly every loan approval. Underwriters know that a business can look strong on paper (high revenue, solid assets, big growth potential) but none of that guarantees you can handle monthly payments.

So, can poor cash flow prevent loan approval? In many cases, yes. Here’s why.

How Stable Cash Flow Demonstrates Your Ability to Repay a Loan

Lenders want cash flow that’s stable, consistent and, ideally, growing. Predictability matters because it tells them what they can count on, not just during a good month, but during an average or even a challenging one. When your cash flow is consistent, lenders can clearly see whether you can repay the loan without straining your business.

Lenders also look at how you manage ups and downs in your cash flow. Every business has slow periods, but lenders pay close attention to the size of those dips and how quickly you bounce back. If your cash flow is steady and your expenses are manageable, lenders see you as lower risk.

Lenders look at a few basic things:

  • Do you have enough cash to comfortably handle unexpected dips or emergency expenses?
  • Are your month-to-month fluctuations predictable or do they jump around too much?
  • Lenders may set guidelines to protect your business and themselves, and they’ll design these based on how steady your cash flow appears.

In simple terms: Strong incoming cash today is far more valuable than big potential revenue later. This can be why strong cash flow loan approval rates are substantially higher.

How Do Lenders Evaluate Business Cash Flow?

Cash flow is a term that gets tossed around a lot in the business world, but it’s more than just money in, money out. When you apply for a term loan, line of credit or other types of funding, lenders focus on tools and reports that give a clear picture of your business’s health. One of the most important tools you’ll need to put together is a cash flow statement for loan approval, which summarizes where cash is coming from, where it’s going and whether you have enough to cover all your obligations.

Understanding DSCR, EBITDA and Bank Statements

Most lenders use at least one of the following to evaluate your cash flow:

  • DSCR (Debt Service Coverage Ratio): Shows whether your current cash flow can comfortably cover debt payments.
  • EBITDA (Earnings Before Interest, Taxes, Depreciation and Amortization): A measure of your business’s earning that shows how easily you can repay debt, ignoring taxes, interest or accounting adjustments.
  • Bank statements: A real-world, real-time view of your cash behavior, showing the actual flow of money in and out — not just accounting summaries.

Lenders also adjust your financials to get a clearer picture, such as:

  • Normalization: Removing unusual or one-time events that could distort your numbers.
  • Add-backs: Including legitimate owner expenses, like your own compensation or even personal expenses that may contribute to your overall cash flow.
  • Seasonality smoothing: Adjusting for predictable ups and downs in cyclical businesses.

However, there are common pitfalls to avoid: Inflated add-backs, inconsistent statements or unclear records can raise red flags and make underwriters skeptical. A clean, transparent cash flow for loan approval helps lenders see your business as reliable and capable of repaying debt.

What Cash Flow Mistakes Can Hurt Business Loan Approval?

Even strong businesses can run into cash flow problems in financing if their timing or internal processes aren’t organized. Small mistakes can make lenders wonder if your business can handle a loan, even if your numbers are solid.

How Late Customer Payments and Large Expenses Affect Your Application

Two issues often cause trouble:

  • Slow customer payments: When clients pay late, your cash flow can look weaker than it truly is. Lenders might think your business struggles to generate cash, even if it’s just a timing issue.
  • Large expenses right before applying: Big purchases or payments made right before you submit a loan application can make it look like your business is short on cash. Even if these are normal business expenses, leaders may see them as a warning sign unless you explain clearly.

Even if these are normal business moves, underwriters interpret them as cash flow strain unless there’s clear context.

How to Improve Cash Flow Before Applying for Business Financing

What cash flow do lenders want to see? Lenders reward preparation. Before applying, strengthen your cash flow to maximize your approval odds for any cash flow business loan.

Speed Up Receivables and Manage Expenses to Strengthen Cash Flow

Practical ways to make your cash flow look stronger and more predictable include:

  • Speed up customer payments: Tighten payment terms, follow up more often or offer small discounts for early payment.
  • Work with vendors: Negotiate flexible payment schedules to smooth outgoing payments.
  • Reduce non-essential spending: So your statements look cleaner and more predictable.
  • Build recurring revenue: Even small subscription-style offerings or retainers can help stabilize cash coming in.

These improvements don’t just enhance cash stability — they also directly improve how cash flow affects loan approval.

Strong Cash Flow Supports Business Financing Approval

At the end of the day, lenders want confidence, and your cash flow tells the clearest story. Whether your numbers are smooth and steady or choppy and unpredictable will heavily influence any business financing cash flow decision.

By understanding and improving your cash flow before applying, you give your business a better chance at faster approvals, better loan terms and long-term financial health.

FAQs

How does cash flow impact business financing approval?

Cash flow affects business financing approval by showing lenders whether your business can repay financing without straining operations. Consistent inflows and manageable expenses demonstrate repayment capacity, while unpredictable fluctuations raise concerns about risk. Lenders evaluate cash flow stability during average months and slower periods, not just strong sales months.

Can poor cash flow prevent financing?

Yes, poor cash flow can prevent business financing approval when lenders doubt your ability to cover debt payments. Unpredictable inflows, late customer payments and large expenses can signal financial strain. Clear explanations of payment timing and unusual expenses help lenders understand your cash flow, but repayment capacity remains essential.

What cash flow do lenders want?

Lenders want stable, consistent cash flow that covers debt payments and operating expenses, including during slower periods. They review debt service coverage, earnings and bank statements to assess repayment capacity. Predictable seasonal fluctuations, manageable expenses and accurate financial records help demonstrate that your business can handle financing.

Brandon Wyson

Brandon Wyson

Content Writer
  • Twitter
  • LinkedIn
  • Facebook
  • Youtube
  • Instagram

Expertise: Expertise: Business communication, small business operations, international trade and importing. 

Years of experience: 9

Brandon is a business writer and former small business owner. Before becoming a full-time writer with Kapitus in 2021, he worked as a local journalist for publications in New York City and Boston.

After building a successful importing business supported with strategic financing, Brandon now uses that firsthand experience to help other small business owners make smarter funding decisions.

Today, he writes practical articles about the day-to-day of running a business, loans and financing strategy. His goal is to break down complex financial topics into clear, actionable guidance so business owners can choose the right financing and keep their businesses moving forward with confidence.

Read More Articles >>

Related Posts

Our trending spaces

October 19, 2026 Fast Business Loans

How Much Working Capital Does Your Small Business Need?

October 19, 2026/by Kapitus
October 16, 2026 Fast Business Loans

How to Prepare for a Business Loan: What Lenders Look For

October 16, 2026/by Kapitus
October 14, 2026 Fast Business Loans

How Cash Flow Impacts Business Loan Approval: What Lenders Look For

October 14, 2026/by Brandon Wyson
Load more
https://kapitus.com/wp-content/uploads/2026/10/shutterstock_1708337185.jpg 5547 8320 Brandon Wyson https://kapitus.com/wp-content/uploads/2024/01/Kapitus_Logo_white-220.webp Brandon Wyson2026-10-14 11:00:062026-10-13 13:35:04How Cash Flow Impacts Business Loan Approval: What Lenders Look For

Trending Topics

Financing
Budgeting
Cash Flow
Grants

Categories

Operating Your Business

Managing Your Money

Small Business Regulations

Managing Your Team

The Economy

Being a Business Owner

Marketing Your Business

Selling Your Products 

Industry Challenges


Industries

  • Automotive
  • Commercial Cleaning
  • Construction
  • Dentists
  • Medical Practices
  • Plumbers
  • Restaurants
  • Trucking

Sign Up For Our Newsletter

Join

Discover

  • Kapitus Difference
  • Resource Center
  • Success Stories

About

  • Privacy Policy
  • Terms of Use Agreement
  • Leadership Team
  • Careers
  • Media Center
  • Kapitus Partner API
  • USA PATRIOT Act

Products

  • Business Loans
  • SBA Loans
  • Line of Credit
  • Equipment Financing
  • Helix® Healthcare Financing
  • Revenue Based Financing
  • Invoicing Factoring
  • Purchase Order Financing

Copyright 2026 Strategic Funding Source, Inc. All rights reserved. Kapitus and the Kapitus logo are registered trademarks of Strategic Funding Source, Inc. Loans made or brokered in California are either by Kapitus LLC, pursuant to License Number 60DBO-198798, or by Kapitus Equipment Finance LLC, pursuant to License Number 60DBO-210433.

Loans may be funded by WebBank. The specific lender will be identified in your agreement.

  • Twitter
  • LinkedIn
  • Facebook
  • Youtube
  • Instagram
Scroll to top